Business Flood Insurance

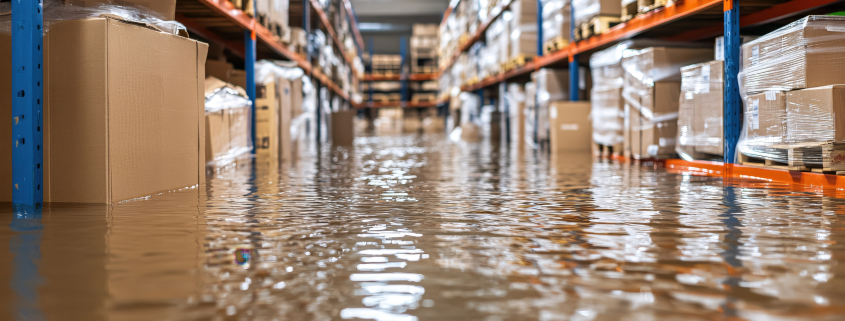
For Colorado business owners, protecting your property from the unexpected is essential to long-term success. While wildfires and snowstorms often grab headlines, flooding remains one of the most overlooked risks. Many commercial property insurance policies do not include flood coverage, which can leave your business financially exposed.

At MountainStorm Insurance, our goal is to help Colorado businesses clearly understand their flood risk and secure the protection they need. Whether you operate a retail shop, manage an office, or lease a small warehouse, knowing your options for business flood coverage is key.

Why Flood Insurance Matters for Colorado Businesses

Flooding can occur almost anywhere, not just in coastal areas. Colorado is particularly vulnerable to:

  • Flash floods from sudden heavy rainfall
  • Rapid snowmelt in spring
  • Overflowing streams and creeks
  • Poor drainage during seasonal storms

Even a small amount of water can lead to significant losses. According to FEMA, just one inch of floodwater can cause more than $25,000 in damage. Without proper insurance, those repair and replacement costs may come entirely out of pocket.

What Does Commercial Flood Insurance Typically Cover?

Business flood insurance helps protect against damage directly caused by rising water from outside your property. It often includes:

  • Structural damage to your building
  • Electrical, plumbing, and HVAC systems
  • Business equipment, inventory, and furnishings
  • Debris removal and cleanup costs

However, it’s important to note that flood insurance does not cover damage from interior plumbing failures or roof leaks—those situations usually fall under your general property insurance.

Who Should Consider Flood Coverage?

Flood insurance isn’t just for businesses in designated high-risk zones. In fact, a large number of claims come from moderate-to-low-risk areas. You should strongly consider flood insurance if:

  • Your property is near rivers, creeks, or other bodies of water
  • You operate in flood-prone areas, including parts of the Front Range and mountain valleys
  • Your business is located on a ground floor or basement level
  • Your lease makes you responsible for insuring your inventory and equipment

Flood Insurance for Your Business

Commercial flood coverage is available through two main channels:

FEMA’s National Flood Insurance Program (NFIP)The NFIP offers policies for building and contents coverage, with standardized limits. It’s a widely accessible option for basic protection.
Private Insurance Options Private insurers may offer flexible coverage, including higher limits and additional protections such as business interruption coverage.

When Should You Secure Coverage?

Flood insurance typically has a 30-day waiting period before it becomes active. That means you can’t wait until a major storm is forecasted. The best time to add flood coverage is before the rainy season or any high-risk periods.

Frequently Asked Questions: Business Flood Insurance in Colorado

Does my commercial property insurance cover flooding?

No. Most property insurance policies specifically exclude flood damage. A separate flood insurance policy is required.

Is flood insurance mandatory for businesses?

Only if your business is in a high-risk flood zone and has a federally backed mortgage. However, it is highly recommended for many others outside of those zones as well.

How much does flood insurance cost for a small business?

Costs vary depending on location, elevation, building features, and desired coverage limits. On average, policies range from several hundred to a few thousand dollars per year.

Can tenants or renters purchase flood insurance?

Yes. Business owners who lease commercial space can purchase a policy to protect their equipment, inventory, and any tenant improvements.

What’s the difference between federal and private flood insurance?

NFIP policies are government-backed with fixed terms, while private carriers may offer more customized plans, faster processing, and optional add-ons.

Flooding can happen when you least expect it—and the cost of recovery without coverage can be devastating. Having the right protection in place can make all the difference.

Connect with a local expert at MountainStorm Insurance to evaluate your flood risk and find a policy that aligns with your business needs. Our team is here to guide you through the process and ensure your Colorado business is protected with confidence and clarity.

Whether you’re looking to supplement your current coverage or explore options for the first time, we’re ready to help—reach out today to get started.

A First-Time Buyer’s Guide to Homeowners Insurance in Colorado

Buying your first home is a major milestone, and with it comes the responsibility of protecting what may be your biggest investment. Whether you’re purchasing a cozy condo in Highlands Ranch or a single-family home on the Front Range, homeowners insurance is an essential part of the process. But if you’re like many first-time buyers in Colorado, navigating the coverage options can feel overwhelming.

At MountainStorm Insurance, we specialize in helping new homeowners across Colorado understand and secure the right protection from day one. Here’s what you need to know to make informed decisions and feel confident in your coverage.

What Is Homeowners Insurance, and Why Do You Need It?

Homeowners’ insurance protects your home and personal belongings from unexpected events like fire, theft, hail, or water damage. It also covers liability in case someone gets injured on your property.

Most mortgage lenders require you to carry insurance to protect their investment, but even if you’re buying without a loan, it’s still one of the smartest ways to safeguard your home and peace of mind.

A good policy offers:

  • Dwelling coverage: Repairs or rebuilds your home if it’s damaged by a covered event
  • Personal property coverage: Protects belongings like furniture, electronics, and clothing
  • Liability protection: Covers legal costs and medical bills if someone is injured on your property
  • Additional living expenses: Pays for hotel stays or rentals if your home becomes uninhabitable due to damage

What Makes Homeowners Insurance in Colorado Unique?

Colorado homeowners face specific risks that influence coverage and costs. These include:

  • Wildfires and smoke damage, especially in foothill and mountain regions
  • Hailstorms, which frequently impact roofs and windows
  • Snow and ice, which can lead to roof collapse or frozen pipes
  • Wind damage, particularly along open plains and ridgelines

Understanding these local factors helps ensure you’re getting a policy that truly protects your home, not just checking a box for your lender.

How Much Coverage Do You Need?

The amount of coverage you need depends on your home’s value, size, location, and what you keep inside it. An experienced local agent can help you calculate:

  • The full cost to rebuild your home (not just market value)
  • Replacement value of your personal belongings
  • Liability limits that reflect your lifestyle and financial situation

If you own high-value items like fine jewelry, art, or outdoor equipment, consider scheduled personal property coverage for additional protection.

Tips for First-Time Homebuyers in Colorado

1. Don’t just go with the cheapest policy
Affordable homeowners insurance is important, but make sure it also offers comprehensive protection. A low premium may come with high deductibles or limited coverage.

2. Bundle and save
Many insurers offer discounts when you bundle home and auto insurance. Ask about available savings.

3. Ask about hail and roof-specific coverage
Some Colorado policies include higher deductibles or limitations for roof damage. Make sure your policy reflects the condition and age of your roof.

4. Understand what’s not covered
Most standard policies do not cover flood damage. If you live near a floodplain or drainage area, you may want to explore separate flood insurance.

Frequently Asked Questions: Homeowners Insurance for First-Time Buyers

Is homeowners’ insurance required in Colorado?

It’s not required by state law, but if you have a mortgage, your lender will almost always require it.

How much does homeowners’ insurance cost in Colorado?

The average annual premium in Colorado is around $1,800–$2,500, but this varies based on location, home size, roof condition, and other factors.

Can I switch insurers after buying a home?

Yes. You can shop around and change providers, even after closing. Just make sure there’s no lapse in coverage.

What deductible should I choose?

Higher deductibles usually lower your premium but increase your out-of-pocket costs during a claim. A $1,000 deductible is common for many first-time buyers.

Does my policy cover wildfires or hail damage?

Yes, but coverage specifics vary. Some insurers in high-risk areas may require higher deductibles or offer limited options. It’s important to discuss this during the quote process.

Buying a home is a huge step, and making sure it’s properly protected should feel just as empowering as the purchase itself.

At MountainStorm Insurance, we take the time to explain every part of your policy, answer your questions in plain language, and help you choose the right homeowners insurance coverage for your new Colorado home.

If you’re a first-time buyer in Highlands Ranch or anywhere across the state, reach out today and let our local team help you feel confident, secure, and ready for the road ahead.

A Retiree’s Guide to Supplemental Insurance in Highlands Ranch

As you enter retirement, understanding your healthcare coverage is essential, especially when it comes to filling the gaps left by Original Medicare. Many retirees are surprised to find that Medicare doesn’t cover all medical costs, which is why Medicare supplemental insurance, also known as Medigap, plays such an important role in your financial and health security.

At MountainStorm Insurance, we proudly serve retirees and seniors in Highlands Ranch and throughout Colorado, helping them navigate supplemental coverage with clarity and confidence. Whether you’re planning for the future or exploring new options during open enrollment, our licensed agents are here to make sure you’re fully informed.

Why Medicare Alone May Not Be Enough

Medicare Parts A and B provide foundational coverage but leave out significant costs, including:

  • Deductibles and co-pays
  • Hospital and outpatient coinsurance
  • Emergency medical care while traveling abroad
  • Extended skilled nursing care or rehabilitation

These out-of-pocket expenses can add up quickly, particularly for retirees on a fixed income or with ongoing medical needs. That’s where a Medicare supplement plan can help.

What Is Medicare Supplemental Insurance (Medigap)?

Medigap policies are sold by private insurance companies and are designed to work alongside Original Medicare. They help cover the “gaps” in Medicare by paying for costs like deductibles, copayments, and coinsurance.

Plans are standardized and labeled Plan A through Plan N, each offering different levels of coverage. While all plans follow federal guidelines, pricing and availability can vary by provider and region.

Who Should Consider a Medigap Plan?

You might benefit from a Medicare supplement plan if you:

  • Want the freedom to see any doctor who accepts Medicare
  • Prefer predictable healthcare costs with fewer surprise bills
  • Travel regularly and want emergency coverage outside the U.S.
  • Have chronic health conditions requiring frequent care

These policies are a great option for retirees who want flexibility, peace of mind, and cost control.

When to Enroll in a Supplemental Plan

The best time to enroll is during your Medigap Open Enrollment Period, which starts the month you turn 65 and are enrolled in Medicare Part B. During this six-month window, you can buy any plan available in your area without undergoing medical underwriting.

If you miss this enrollment period, you can still apply later, but your acceptance and premium cost could depend on your health history.

Frequently Asked Questions: Medicare Supplement Insurance in Colorado

Does Medigap cover prescriptions?

No. You’ll need to enroll in a Medicare Part D plan for prescription drug coverage.

Can I have both a Medigap and Medicare Advantage plan?

No. You must choose one or the other—they cannot be used together.

How much does a Medigap plan cost in Highlands Ranch?

Costs vary depending on the plan, your age, tobacco use, and where you live. We can provide personalized quotes based on your needs.

Will I be able to keep my doctor?

Yes, as long as your doctor accepts Medicare, you can continue seeing them with any Medigap plan.

What if I travel part-time or move between states?

Medigap plans are generally portable across states, and some plans include emergency foreign travel coverage. Let us know your travel plans so we can recommend the best fit.

Choosing the right supplemental plan is a smart way to protect your health and your retirement savings, but it can feel overwhelming without the right guidance.

At MountainStorm Insurance, we specialize in helping Colorado retirees find the right Medicare supplemental insurance for their needs and budget. If you’re in Highlands Ranch or the surrounding area, our licensed advisors are ready to walk you through your options and make the process easy and stress-free.

Call or message us today to schedule your free Medicare supplement review, and let’s make sure you’re fully covered for the road ahead.

Seasonal Tips for Insuring ATVs and RVs in Colorado

As adventure season approaches in Colorado, it’s time to gear up—on the trails, in the mountains, and on the road. Whether you’re preparing your ATV for backcountry rides or planning weekend getaways in your RV, having the right seasonal insurance coverage is just as important as a full tank of gas.

At MountainStorm Insurance, we’re proud to serve outdoor enthusiasts across Colorado, including families in Highlands Ranch, where access to scenic terrain is right around the corner. If you own an ATV, RV, or other recreational vehicle, here’s what you need to know before heading out this season.

Why Insuring Recreational Vehicles Matters

ATVs, campers, and motorhomes face unique risks—both on and off the road. Unlike your daily driver, these vehicles often travel through rugged environments, sit idle for months at a time, or haul valuable gear. Without the right policy in place, even a small accident or theft could become a major financial burden.

And remember: most standard auto and homeowners insurance policies do not fully cover these types of vehicles.

Key Insurance Considerations for ATVs & RVs

Know When to Start (and Update) Your Coverage

Spring and summer are the most popular times for off-road riding and road trips, which means it’s smart to review or reactivate your coverage before the season begins.

  • If your ATV or RV has been in storage, make sure your policy reflects current use.
  • Let your insurance advisor know if you plan to use your RV as a full-time residence or travel out of state.
  • For ATVs, check if you’re covered on public trails or just on private property.

Evaluate Liability Protection

Just like any other vehicle, ATVs and RVs need liability coverage in case you’re responsible for injury or property damage. For RVs, this is especially important when parked at campgrounds or traveling through unfamiliar areas.

Protect Against Damage & Theft

Seasonal coverage should also include comprehensive and collision protection to help with:

  • Damage from fire, hail, or falling objects
  • Vandalism or theft during storage
  • Off-road accidents (for ATVs)
  • Animal-related damage while camping

Consider Specialized Add-Ons

Depending on how you use your recreational vehicle, ask your insurance agent about:

  • Vacation liability for accidents at a campsite
  • Personal belongings coverage for gear and electronics inside your RV
  • Roadside assistance for breakdowns on the highway or trail

Bundle and Save

If you already have auto, home, or other policies with us, bundling your recreational vehicle insurance could help you save while streamlining your coverage.

Frequently Asked Questions: ATV and RV Insurance in Colorado

Do I need to insure my ATV if I only use it on private land?

It’s still recommended. While coverage may not be legally required on private property, accidents, theft, and damage can happen anywhere. Insurance helps protect your investment.

Is RV insurance required in Colorado?

Yes—if your RV is motorized (Class A, B, or C), Colorado requires liability insurance. Towable RVs like campers and trailers may be covered under your auto policy, but often need additional protection.

Can I pause my insurance during the off-season?

Some insurers offer storage or seasonal policies, but be careful—dropping coverage entirely may leave you exposed to theft, weather damage, or fire while in storage.

Is my gear inside the RV covered by insurance?

It can be, but not always. Ask about personal effects coverage to protect your camping equipment, tools, or electronics stored in your RV.

Will my auto policy cover my trailer or ATV during transit?

Your auto policy may provide limited coverage while towing, but not for the contents or full value of the trailer or ATV. Dedicated coverage offers better protection.


It can be, but not always. Ask about personal effects coverage to protect your camping equipment, tools, or electronics stored in your RV.

Don’t let insurance be an afterthought when adventure calls. Whether you’re hitting the trails near Highlands Ranch or setting out for a cross-country road trip, MountainStorm Insurance is here to help you find the right seasonal protection for your ATV or RV.

Let’s make sure you’re ready, on and off the road. Reach out today for personalized coverage that fits your recreational lifestyle.

Do Roofers Really Need Specialized Insurance

Roofing is one of the most high-risk trades in the construction industry. Whether you’re a solo contractor or manage a full crew, working at heights, handling sharp tools, and navigating unpredictable weather conditions creates unique risks every day on the job. That’s why standard business insurance isn’t enough.

Roofing contractors in Colorado need specialized insurance coverage that accounts for the specific dangers they face. At MountainStorm Insurance, we help roofing businesses secure protection that matches their operational needs, so you can stay focused on the job without worrying about liability or financial loss.

Why General Business Insurance Doesn’t Cut It

Many roofing businesses make the mistake of assuming a basic general liability policy offers full coverage. While it does provide a foundational level of protection, it’s often not tailored to the real-world risks of roofing work.

For example, general policies may exclude:

  • Injuries from working at height
  • Water damage due to improper installation
  • Property damage from falling tools or debris
  • Employee injuries while on a steep-slope roof

Without proper coverage, even a minor incident can result in major out-of-pocket expenses, lawsuits, or contract disputes.

What Does Roofing Business Insurance Include?

Tailored insurance for roofing contractors typically includes the following core coverages:

General Liability Insurance

Protects against third-party property damage or bodily injury. Essential for job site incidents like a falling shingle hitting a parked vehicle or damage to a client’s home during a project.

Workers’ Compensation

Mandatory in Colorado if you have employees. Covers medical bills, lost wages, and rehabilitation if a crew member is injured on the job.

Commercial Auto Insurance

Covers vehicles used to transport tools, equipment, and crew members. Also includes liability in the event of a work-related vehicle accident.

Inland Marine (Tool & Equipment Insurance)

Protects your tools, ladders, generators, and other mobile equipment from theft, vandalism, or damage while on the move or on-site.

Professional Liability (Errors & Omissions)

Covers claims related to faulty workmanship or design errors, such as a roof that leaks due to incorrect material application.

Umbrella Insurance

Adds an extra layer of protection above the limits of your primary policies. Ideal for contractors who want to safeguard against large claims or lawsuits.

Why Colorado Roofers Face Unique Risks

Roofers in Colorado contend with rapid weather changes, hailstorms, snow loads, and high winds, all of which increase the chance of job-related accidents or structural issues. Because of this, insurance providers often consider roofing a high-risk trade, which means policies must be carefully customized to meet underwriting requirements and local regulations.

Additionally, many homeowners and commercial clients won’t hire a roofer without proof of insurance, particularly general liability and workers’ compensation. Not being properly insured can cost you bids and damage your business reputation.

Frequently Asked Questions: Roofing Contractor Insurance in Colorado

Is roofing insurance legally required in Colorado?

While Colorado does not require roofers to be licensed at the state level, workers’ compensation is mandatory if you employ others. General liability is not required by law, but most clients and contracts will demand it.

How much does roofing contractor insurance cost?

Costs vary based on your business size, coverage limits, number of employees, and claims history. On average, small roofing contractors can expect to pay between $2,000 and $6,000 annually for a complete insurance package.

Does my policy cover subcontractors?

Typically, subcontractors need to carry their own insurance. However, some policies allow you to add them for an additional cost. Always confirm coverage requirements with your insurer before hiring.

What happens if a customer claims my work was defective?

That’s where professional liability insurance comes in. It helps protect you from claims involving errors in your work, even if the mistake was unintentional.

Can I bundle my coverages into one plan?

Yes. Many roofing businesses choose a Business Owner’s Policy (BOP), which combines general liability and property coverage. Additional options like inland marine and commercial auto can be added for full protection.

Roofing is demanding work, and it comes with serious risk. Don’t leave your business exposed with generic coverage.

Let MountainStorm Insurance help you build a specialized insurance plan that fits your trade, your team, and your future. Reach out today to talk with an advisor who understands the demands of the roofing industry and can guide you toward the coverage that protects what matters most.

umbrella insurance

For families and individuals with substantial assets, protecting your financial future requires more than just standard insurance. While policies like homeowners and auto insurance provide essential coverage, they often come with limits that could leave you exposed to significant financial risks in the event of large claims or lawsuits. Umbrella insurance offers an additional layer of protection, covering high-value properties and shielding against costly liabilities that exceed the coverage of your primary policies.

In Highlands Ranch, where many households own luxury homes, vehicles, and recreational assets, umbrella insurance is a vital tool for safeguarding wealth and minimizing risks.

What is Umbrella Insurance?

Umbrella insurance provides extended liability coverage that kicks in when the limits of your existing policies, such as auto or home insurance, are exhausted. This additional protection is designed to cover a wide range of scenarios, ensuring your assets and financial stability are secure.

Key features of umbrella insurance include:

  • Excess liability coverage for claims that exceed your existing policy limits.
  • Coverage for situations not typically included in standard policies, such as libel, slander, or false arrest.
  • Legal protection, including court fees, settlements, and damages arising from covered claims.

The Importance of Comprehensive Coverage

Standard policies often have liability caps that may not fully address high-value claims. Without umbrella insurance, you could be responsible for covering costs that exceed these limits, putting your assets at risk.

Why standard insurance may fall short:

  • Severe car accidents involving multiple injuries or high medical costs can quickly surpass auto liability limits.
  • Incidents on your property, such as a guest injury or structural damage to a neighbor’s home, might result in lawsuits that exceed your homeowner’s insurance.
  • Risks associated with owning rental properties or recreational vehicles often require more coverage than standard policies provide.
  • Umbrella insurance fills these gaps, offering peace of mind and ensuring you’re protected in high-stakes situations.

How Umbrella Insurance Protects Your Lifestyle

For residents of Highlands Ranch, umbrella insurance is particularly valuable for those with high-value homes, substantial savings, or a portfolio of luxury assets. It extends protection to all areas of your life, from personal liability to recreational risks.

Scenarios where umbrella insurance provides vital protection:

  • Liability claims related to boating or recreational vehicle accidents.
  • Lawsuits stemming from injuries occurring at your home or on your rental property.
  • Claims involving defamation, such as libel or slander, are often excluded from standard policies.

Benefits of umbrella insurance include:

  • Broad coverage that protects your assets from unforeseen risks.
  • Financial security for high-value claims, helping you avoid out-of-pocket expenses.
  • Added peace of mind when managing luxury properties or engaging in higher-risk activities.

Customizing Your Umbrella Insurance

Choosing the right umbrella insurance requires careful consideration of your lifestyle, assets, and potential liabilities. Policies can be tailored to meet your specific needs, ensuring that every aspect of your financial picture is protected.

To optimize your coverage:

  • Evaluate the total value of your assets, including real estate, savings, and luxury vehicles.
  • Review the liability limits on your existing home, auto, and other insurance policies to identify any gaps in coverage.
  • Consult with a provider like MountainStorm Insurance for personalized guidance on bundling policies and maximizing savings.

Why Highlands Ranch Residents Choose MountainStorm Insurance

As a trusted local provider, MountainStorm Insurance understands the unique needs of Highlands Ranch residents and specializes in crafting customized umbrella policies that deliver comprehensive protection.

Advantages of choosing MountainStorm Insurance:

  • Local expertise in high-value and luxury asset coverage.
  • Tailored solutions for bundling home, auto, and umbrella policies, offering convenience and cost savings.
  • Dedicated service to ensure every client’s unique risks are addressed.
  • With MountainStorm Insurance, you can feel confident that your financial future is secure, no matter what life brings.

Protect Your Assets with Confidence

Life’s uncertainties shouldn’t put your financial stability at risk. Umbrella insurance provides the additional protection you need to safeguard your high-value assets, ensuring peace of mind for you and your family. Contact MountainStorm Insurance today to learn how a customized umbrella policy can protect your wealth and enhance your coverage.

Shield your financial future with umbrella insurance. MountainStorm Insurance offers tailored solutions for Highlands Ranch residents with high-value assets.

smart home insurance

In today’s connected world, smart home technology is transforming how we live, offering convenience, security, and energy efficiency at our fingertips. For tech-savvy millennials, a home equipped with smart thermostats, security cameras, and voice-activated devices represents not just comfort but a significant investment. Protecting this tech-enabled lifestyle requires tailored smart home insurance that covers both traditional and modern risks.

Whether you’re in Highlands Ranch or elsewhere in Colorado, understanding how smart home insurance works ensures your cutting-edge setup is secure against unexpected events.

Why Smart Home Insurance is Essential

While traditional homeowners insurance protects your property and belongings, smart homes come with unique needs. The integration of high-value devices, interconnected systems, and potential cybersecurity risks requires insurance policies designed for the digital age.

Benefits of smart home insurance include:

  • Comprehensive Coverage: Protects expensive tech devices like security cameras, smart locks, and smart appliances.
  • Cybersecurity Protection: Covers losses from hacking or unauthorized access to your connected devices.
  • Liability for Tech Failures: Protects you if a malfunction, such as a thermostat failure, leads to damage like frozen pipes or electrical fires.

Key Features of Smart Home Insurance

To adequately protect your tech-enabled home, look for policies that address the following areas:

  • Device Coverage: Ensures replacement costs for smart devices damaged by fire, theft, or natural disasters.
  • Cyber Liability Insurance: Covers data breaches, identity theft, and other risks tied to hacking incidents.
  • Utility Service Coverage: Addresses issues caused by service interruptions that disrupt your smart systems, such as power outages.
  • Add-On Options: Some providers offer additional protections, such as extended warranties for connected devices.

How Smart Devices Can Lower Insurance Costs

The beauty of smart home technology is that it not only enhances your quality of life but can also reduce your insurance premiums. Many insurers offer discounts for homeowners who install smart safety and security systems.

Devices that can help you save include:

  • Smart Security Systems: Burglar alarms, cameras, and doorbell cameras reduce the risk of theft and vandalism.
  • Smart Smoke and Carbon Monoxide Detectors: Early detection reduces the risk of major damage, lowering claims costs.
  • Leak Detectors: Prevent water damage from leaks, frozen pipes, or overflows, reducing the likelihood of expensive repairs.

By incorporating these systems, you not only protect your home but also enjoy potential savings on your premiums.

Tips for Insuring Your Smart Home

Protecting your smart home requires thoughtful planning and an understanding of your policy options. Here’s how to get started:

Evaluate Your Devices
Take an inventory of all your connected devices, including their make, model, and value. Knowing what you own helps you choose coverage that matches your needs.

Look for Tech-Specific Policies
Not all homeowners insurance policies are designed for smart homes. Look for providers that offer tech-specific options, including coverage for data breaches and device failures.

Consider Cybersecurity
For homes with internet-connected devices, cyber insurance is essential. This add-on protects against risks like hacking, identity theft, and ransomware attacks.

Bundle Policies
If you’re insuring a smart home in Highlands Ranch, consider bundling with auto or other policies. Local providers like MountainStorm Insurance offer discounts for multi-policy customers.

Why Millennials are Leading the Smart Home Insurance Trend

Millennials are adopting smart home technology at a rapid pace, drawn by its blend of innovation and practicality. From energy-efficient thermostats to AI-enabled voice assistants, these systems represent significant financial and personal value.

For millennials in Colorado, specialized insurance provides the peace of mind that comes with knowing their investments in technology are secure. Coverage tailored to smart homes is especially relevant as devices become more advanced and interconnected.

How MountainStorm Insurance Protects Your Smart Home

As a trusted provider serving Highlands Ranch and the greater Colorado area, MountainStorm Insurance offers personalized solutions for modern homeowners.

What makes MountainStorm a top choice for smart home insurance:

  • Tech-Specific Coverage: Policies designed to protect your smart home systems and connected devices.
  • Cybersecurity Options: Added protection for online threats targeting your home network.
  • Online Quotes for Convenience: Get a quote quickly through MountainStorm’s easy-to-use online tools.
  • Local Expertise: Agents who understand the unique needs of Colorado homeowners.

Whether you’re upgrading your smart home or need coverage for an established system, MountainStorm Insurance ensures you’re protected.

Securing the Future of Your Tech-Enabled Home

Smart homes represent the future of living, combining convenience with cutting-edge technology. But with innovation comes responsibility—protecting your investment and ensuring your home is secure from both physical and digital threats.

Contact MountainStorm Insurance today to explore smart home insurance options tailored to your lifestyle. With comprehensive coverage and local expertise, you’ll have the peace of mind to enjoy every aspect of your tech-enabled life.

protecting your boat

For Colorado boat owners, the joy of exploring lakes and waterways is unmatched. However, owning a boat comes with unique risks that standard insurance policies may not fully cover. Specialty boat insurance is designed to address these challenges, offering tailored protection that goes beyond general policies. Whether you’re navigating Colorado’s scenic reservoirs or storing your vessel during the off-season, understanding the importance of specialized insurance ensures peace of mind and safeguards your investment.

What is Specialty Boat Insurance?

Specialty boat insurance provides comprehensive protection for your vessel, addressing risks that standard policies often overlook. Unlike general auto or homeowner’s insurance, which may offer limited coverage for watercraft, specialized policies are designed with boat owners in mind, covering a wide range of potential issues.

Key features of specialty boat insurance include:

  • Hull and Equipment Coverage: Protects against damage to your boat, motor, and attached equipment.
  • Liability Protection: Covers legal and medical expenses if your boat causes injury or damage to others.
  • Towing and Assistance: Offers roadside and on-water assistance for breakdowns or emergencies.
  • Uninsured Boater Coverage: Provides financial protection if you’re involved in an accident with an uninsured vessel.

Why Standard Policies May Not Be Enough

Many boat owners assume their homeowners or auto insurance will provide sufficient coverage for their vessel. While these policies may offer limited protection, they often exclude critical risks specific to boating.

Limitations of standard insurance include:

  • Coverage is typically capped at low amounts that may not reflect your boat’s value.
  • Exclusions for incidents occurring on water, such as collisions or sinking.
  • No coverage for specialized equipment like GPS systems or trolling motors.

Without specialty insurance, boat owners risk significant financial losses in the event of theft, damage, or liability claims.

How Specialty Insurance Protects High-Value Vehicles

Boats and other recreational vehicles, like RVs and ATVs, represent significant investments. Specialty insurance ensures these assets are adequately protected, allowing you to enjoy your hobbies without worry.

Specialty insurance covers risks such as:

  • Accidental damage from collisions or natural disasters.
  • Theft or vandalism, both on and off the water.
  • Damage caused during transport or while in storage.
  • Liability claims resulting from on-water incidents.

By tailoring coverage to your specific vehicle, specialty policies provide peace of mind and financial security that generic plans cannot match.

Benefits of Specialty Boat Insurance

When it comes to safeguarding your boat, the benefits of specialized insurance extend beyond basic coverage.

  • Comprehensive Protection: Includes damage from storms, accidents, and theft, whether your boat is in use or stored.
  • On-Water Assistance: Emergency services like towing, fuel delivery, or jump-starting help you handle unexpected issues.
  • Flexible Policy Options: Tailored coverage lets you select the features you need, such as coverage for personal items or fishing equipment.
  • Seasonal Adjustments: Policies can be customized to reflect seasonal use, saving money during inactive periods.

Choosing the Right Insurance for Your Needs

When selecting a specialty insurance provider, consider these tips to ensure you’re getting the best coverage:

Assess Your Boat’s Value and Usage
Consider your boat’s market value, age, and how often it’s used. A high-performance speedboat may require different coverage than a family-friendly pontoon.

Look for Comprehensive Coverage
Ensure the policy covers key risks, including accidents, natural disasters, theft, and liability. Add-ons like uninsured boater coverage and personal effects protection can enhance your plan.

Compare Providers
Research multiple insurance companies to find competitive rates and robust coverage options. Local providers like MountainStorm Insurance offer expertise tailored to Colorado’s unique boating environment.

Bundle Policies
If you own other recreational vehicles, such as ATVs or RVs, bundling your policies can lead to discounts and simplified management.

Why MountainStorm Insurance is the Right Choice

For Colorado boat owners, MountainStorm Insurance offers specialized insurance solutions that cater to the state’s unique boating conditions.

What sets MountainStorm apart:

  • Expertise in recreational and specialty vehicle coverage.
  • Flexible policies tailored to seasonal use.
  • Local agents who understand the needs of Colorado boaters.
  • Discounts for bundling boat, RV, and ATV insurance.

By choosing a provider that focuses on specialty insurance, you’ll have peace of mind knowing your boat is protected whether it’s out on the water or safely stored at home.

Protect Your Adventures

Owning a boat is about embracing adventure, creating memories, and enjoying the great outdoors. Don’t let inadequate insurance put your investment or peace of mind at risk. Specialty boat insurance ensures you’re ready for every season and every trip, no matter what challenges arise.

Contact MountainStorm Insurance today to explore comprehensive, customized policies that protect your boat and other recreational vehicles.

M

bundle insurance policies

Highlands Ranch, known for its family-friendly atmosphere, is a community where financial security and family well-being are priorities. For families juggling the costs of homeownership, transportation, and life’s unexpected events, bundling insurance policies is a smart and practical way to save money and simplify their lives. By consolidating home, auto, and life insurance under one provider, families can enjoy discounts, comprehensive coverage, and personalized service tailored to their unique needs.

What is Insurance Bundling?

Insurance bundling involves purchasing multiple insurance policies—such as home, auto, and life insurance—from the same provider. This strategy offers several benefits, particularly for families, who often require a range of coverage types to protect their assets and loved ones.

Key advantages of bundling include:

  • Cost Savings: Many providers offer significant discounts when you bundle policies, reducing overall premiums.
  • Simplified Management: Coordinating policies with a single provider streamlines billing, renewals, and customer support.
  • Comprehensive Protection: Bundling ensures all aspects of your family’s needs are covered seamlessly, avoiding gaps in coverage.

The Financial Benefits of Bundling Insurance

For families in Highlands Ranch, where the cost of living includes investments in homes, vehicles, and long-term planning, finding ways to save money is always welcome. Bundling insurance policies is a simple yet effective way to achieve financial benefits.

  • Multi-Policy Discounts: Many insurers provide discounts ranging from 10% to 25% when you bundle policies, helping families save hundreds annually.
  • Reduced Deductibles: Some providers offer a single deductible for claims affecting multiple policies, such as storm damage impacting both your home and car.
  • Loyalty Perks: Bundling fosters long-term relationships with insurers, often leading to additional discounts or premium benefits over time.

Convenience and Peace of Mind

Managing multiple policies can be overwhelming, especially for busy families balancing work, school, and extracurricular activities. Bundling simplifies insurance management, allowing families to focus on what matters most.

Key conveniences include:

  • A single point of contact for all insurance questions and claims.
  • Consolidated billing, reducing the risk of missed payments.
  • Coordinated coverage for seamless protection during life changes, such as moving or adding a new vehicle.

By bundling policies, families can streamline their insurance experience, making it easier to maintain coverage while ensuring no important details are overlooked.

Comprehensive Coverage for Families

Families in Highlands Ranch face diverse risks, from severe weather to unexpected medical expenses. Bundling policies help address these risks holistically by offering tailored coverage solutions.

  • Home Insurance: Protect your most significant asset from natural disasters, theft, or liability claims.
  • Auto Insurance: Ensure all family vehicles are covered for accidents, liability, and comprehensive damages.
  • Life Insurance: Provide financial security for your loved ones, ensuring their needs are met even during life’s uncertainties.

Life Insurance for Parents: A Key Component of Bundling

For parents, life insurance is a critical part of long-term family planning. Including life insurance in a bundled policy offers added financial security while benefiting from the discounts bundling provides.

Benefits of bundling life insurance include:

  • Affordable premiums with bundled discounts.
  • Simplified management alongside other policies.
  • Assurance that your family’s financial future is secure.

By bundling life insurance with home and auto coverage, parents can create a comprehensive plan that safeguards their family’s assets and well-being.

Tips for Effective Bundling

To maximize the benefits of bundling, families in Highlands Ranch should consider these steps:

  • Evaluate Your Coverage Needs: Assess your family’s home, auto, and life insurance needs to ensure comprehensive protection.
  • Compare Providers: Research insurers offering competitive discounts and family-focused services.
  • Ask About Add-Ons: Consider additional options, such as umbrella policies, to enhance protection.
  • Review Regularly: Reassess your bundled policies annually to ensure they still meet your family’s needs.

Common bundled coverage combinations include:

  • Home, auto, and life insurance.
  • Auto and renters insurance for young families starting out.
  • Home, auto, and umbrella policies for larger households seeking extended protection.

Why Highlands Ranch Families Choose MountainStorm Insurance

MountainStorm Insurance understands the unique needs of Highlands Ranch families, offering tailored bundling options that prioritize savings, simplicity, and protection. With a commitment to personalized service, MountainStorm helps families find the right balance of coverage for their home, auto, and life insurance needs.

Why families trust MountainStorm Insurance:

  • Flexible policy options for families of all sizes.
  • Competitive discounts for multi-policy bundles.
  • Local agents who understand the specific risks and needs of Highlands Ranch families.

Taking the step to bundle insurance policies can make a significant difference for families seeking financial security and peace of mind. Contact MountainStorm Insurance today to explore bundling options designed with your family in mind.

seasonal tips for motor insurance

Highlands Ranch is a playground for outdoor enthusiasts, offering trails, lakes, and open spaces perfect for exploring with your ATV, RV, or boat. With seasonal changes impacting when and how these vehicles are used, having the right insurance strategy is key to protecting your investments and ensuring peace of mind. By understanding your coverage options and making seasonal adjustments, you can maximize protection while managing costs.

Why Seasonal Coverage Matters

Seasonal insurance allows you to adapt your coverage based on your vehicle’s usage. For many in Highlands Ranch, ATVs and RVs see the most action in warmer months, while boats come out for summer lake adventures. Adjusting your insurance during off-peak times can help save money while keeping your vehicles protected.

Benefits of seasonal coverage include:

  • Cost savings from reduced premiums during inactive months.
  • Year-round protection against non-use risks like theft, fire, or weather damage.
  • Flexible policies tailored to how and when you use your vehicles.

Tips for ATV Insurance in Highlands Ranch

ATVs are a go-to choice for trail riding and exploring the beautiful backcountry around Highlands Ranch. To ensure you’re fully protected, here’s what to consider for ATV insurance:

  • Customize your coverage to reflect seasonal use. During off-peak months, when your ATV is in storage, reduce your policy to comprehensive coverage. This protects against theft or damage without the added cost of collision or liability coverage.
  • Bundle your ATV insurance with other policies. If you own an RV or boat, bundling all your outdoor vehicle insurance with a single provider like MountainStorm Insurance can save money and streamline policy management.
  • Prioritize liability protection. Even experienced riders can encounter accidents. Liability insurance ensures you’re covered for medical expenses or legal claims resulting from an incident involving others.

Seasonal Tips for RV Insurance

RVs are a favorite among Highlands Ranch residents for camping trips and cross-country adventures. Whether you use your RV seasonally or year-round, these tips can help you manage your coverage effectively:

  • Adjust your policy during storage months. Comprehensive-only coverage can save you money while still protecting your RV from theft, vandalism, or weather-related damage.
  • Evaluate whether you need full-timer coverage. If your RV is your primary residence, this specialized policy extends protection to personal belongings and increases liability limits.
  • Add roadside assistance. Seasonal travel can lead to breakdowns, especially on longer trips. Roadside assistance covers towing, flat tire repairs, and fuel delivery, ensuring you’re never stranded.

Boat Insurance for Colorado Adventures

While boats are typically associated with summer fun, they still require year-round protection, even when in storage. For boat owners in Colorado, these tips ensure comprehensive coverage:

  • Include lay-up period discounts in your policy. Many providers offer reduced premiums for boats stored during the winter.
  • Confirm coverage for accessories. Items like trailers, fishing equipment, and electronics should be covered under your boat insurance policy.
  • Ensure coverage for non-use risks. Theft, vandalism, and weather damage can occur even when your boat is not in use, making comprehensive protection essential.

Preparing for the Outdoor Season

As you gear up for the next adventure-filled season, take these proactive steps to optimize your ATV, RV, and boat insurance:

  • Review and update your policies annually. Ensure your coverage aligns with your vehicle’s current value and your usage patterns.
  • Secure vehicles during off-seasons. Store them in weatherproof locations to minimize risks and ensure compliance with your insurance policy’s terms.
  • Leverage available discounts. Ask your provider about savings for multi-policy bundles, safety features, or lay-up periods.

Benefits of local providers like MountainStorm Insurance include:

  • Flexible seasonal adjustments tailored to your lifestyle.
  • Comprehensive bundling options for ATV, RV, and boat insurance.
  • Personalized guidance from agents familiar with Highlands Ranch’s unique outdoor scene.

By tailoring your coverage to your specific needs, you can enjoy Highlands Ranch’s great outdoors worry-free. Contact MountainStorm Insurance today to explore affordable, community-focused insurance solutions for your ATV, RV, and boat.